Manufacturing: Enhanced Costing Logic for Overissued Inventory
When you issue materials to a production order and the issued quantity exceeds the on-hand quantity, the stock balance becomes negative. At that point, the system uses the item's current cost, which is determined by its valuation method. However, if new stock later arrives at a different cost, the cost used for the material issue will no longer match the actual cost recorded in the receipt.
Depending on how the system handles this difference, your production work-in-process values may appear out of sync with your general ledger entries. Ultimately, the mismatch can lead to misreported actual production costs, complex reconciliations, and potential confusion during the financial month-end close.
In MYOB Acumatica 2026.1.1, cost variances caused by negative inventory are posted to a dedicated WIP Variance Account, while true production costs continue to be posted to the regular WIP Account. As a result:
- Production costs are reflected consistently across reports.
- Reconciliation of the WIP report and the general ledger becomes easier.
- Overall financial data becomes more accurate and reliable.
Setting Up the GL Accounts
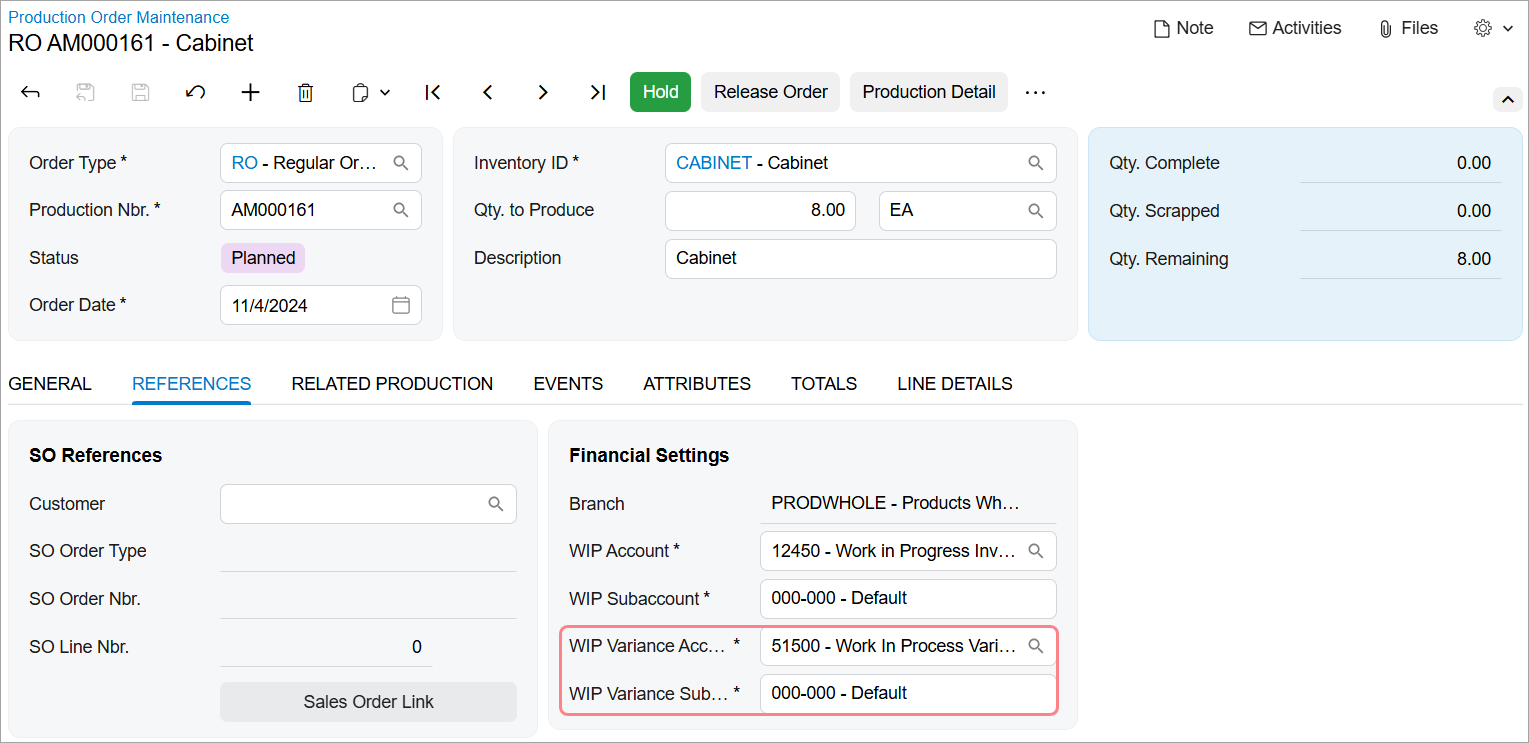
To ensure that the system uses the correct GL accounts to post the costs of the production order, open the References tab of the Production Order Maintenance (AM201500) form—as shown below—and verify the WIP Account and WIP Variance Account.
Posting to the WIP Variance Account
To record the cost variance portion of a transaction, the system now uses the WIP Variance Account when posting journal transactions that offset negative inventory resulting from receipts, issues, adjustments, transfers, or kit assemblies.